FREE LIVE MASTERCLASS · October 1 · 7:00 PM ET · ZOOM
FREE LIVE MASTERCLASS
October 1 · 7:00 PM ET · ZOOM
Make The Money You Already Earn Do 3 Jobs:
Pay The Mortgage Down Faster. Build An Investment Portfolio. Put Your Tax Bracket To Work.
No spam. Your confirmation and a couple of
reminders before we go live.
No spam. Your confirmation and a couple of reminders before we go live.
Make The Money You Already Earn Do 3 Jobs:
Pay The Mortgage Down Faster. Build An Investment Portfolio. Put Your Tax Bracket To Work.
No spam. Your confirmation and a couple of reminders before we go live.
Free. Instant. Nothing to buy, no call required to read it. Just math your bank has never laid out.
Most high earners pay down the house and hope.
This masterclass walks you through the 3 steps that make your mortgage, your paycheque, your investments and your taxes work together, so the same income builds a lot more.
No earning more. No picking stocks. No selling the house.
Live only. Save your seat below.
Real Files. Real Numbers.
Two anonymized files from my desk,
plus the math on one dollar.
THE SAME $10,000, TWO WAYS.
As a lump sum against the mortgage: about $500 a year saved.
One job, then it's locked in drywall.
Contributed to your RRSP past the bracket line: roughly $4,800 back at tax time, with the refund assigned a job. Same $10,000, and that's only 1 of the 3 moves.
Real Files. Real Numbers.
Two anonymized files from my desk, plus the math on one dollar.
Two anonymized files from my desk,
plus the math on one dollar.
THE SAME $10,000, TWO WAYS.
As a lump sum against the mortgage: about $500 a year saved.
One job, then it's locked in drywall.
Contributed to your RRSP past the bracket line: roughly $4,800 back at tax time, with the refund assigned a job. Same $10,000, and that's only 1 of the 3 moves.
CASE FILE #1
Dual-income IT couple · household ~$250K · $1.4M GTA home, $600K owing
$800K of equity sitting idle while they threw extra payments at the mortgage and built retirement from monthly cash flow alone
We restructured so the paycheque accelerates the mortgage while the equity builds productive investment assets beside it
A. & A., GTA
CASE FILE #2
Couple, early 50s · strong income, real equity, RRSPs topped up
They knew the structure needed to change and said "next year" for 5 straight years
We coordinated the mortgage, RRSP contributions, CRA refunds and investments into one plan
M. & S., GTA
THE TWO CHOICES
You have $10,000 of spare money.
You have two options.
Put it against the mortgage
You save about $500 in interest this year. That's the entire return. Small, certain, and gone.
PUT IT TO WORK
It earns a return in the market, becomes an asset you actually own, and, structured properly, the cost of the money you use is generally tax-deductible.
For a household earning well and sitting on real equity, the second path is the one your bank has never laid out in plain numbers. The playbook lays it out.
WHAT
YOU'LL
LEARN
The Two Assets You Own That Earn Nothing
Your equity has been sitting in drywall earning 0% since the day you bought. Your tax bracket has been treated as pure pain. The playbook shows you both as what they actually are: the two halves of an engine.
The Move Your Bank Has Never Laid Out
The worked example, in round numbers: how accessed equity gets put to work so you keep the difference between what money costs and what it earns. Every figure labelled, every figure checkable.
Why Your Bracket Is The Lever, And Yours Runs At Full Strength
Past $181,440 of individual income in Ontario, the tax system starts paying its biggest rewards on exactly the moves you're now positioned to make. Deductible borrowing costs. A $10,000 RRSP contribution returning roughly $4,800. Per person.
The Honest Limits
What this strategy is, what it costs, where the risk lives, and who it's wrong for. Written plainly, because you were going to stress-test it anyway.
Sound Familiar?
The mortgage gets paid. The RRSP gets topped up.
You're doing the responsible thing.
And every spring the tax bill lands and you wonder
where the raise went.
You've been handed tactics your whole life. A better rate.
A budgeting app. Tactics polish one room. Your wealth falls through the floor between the rooms.
The mortgage gets paid. The RRSP gets topped up. You're doing the responsible thing.
And every spring the tax bill lands and you wonder where the raise went.
You've been handed tactics your whole life. A better rate. A budgeting app. Tactics polish one room. Your wealth falls through the floor between the rooms.
THIS IS FOR YOU IF:
THIS IS FOR YOU IF:
Your household earns $200K+ (and the math sharpens further once either of you crosses $181,440 individually)
You own a GTA home with serious equity in it, $500K+ for most of my files
Your broker, advisor, and accountant have never sat in the same room
You're tired of "earn more" being the only answer
SKIP THIS IF:
No T4 (commission or self-employed runs differently)
You're still carrying high-interest consumer debt
SKIP THIS IF:
No T4 (commission or self-employed runs differently)
You're still carrying high-interest consumer debt
EVEN IF YOU
Were told borrowing to invest is "too risky" (it carries real risk, and sizing it properly for your file is exactly what the session covers)
Think rates are too high for this to work (what matters is the gap between what you borrow at and what you earn)
Already have an advisor and don't want to fire anyone
Think 45 is too late to change the next decade
Want to see the math before you believe a word (good, that's the session)
If that's you, I want you in the room.
EVEN IF YOU
Were told borrowing to invest is "too risky" (it carries real risk, and sizing it properly for your file is exactly what the session covers)
Think rates are too high for this to work (what matters is the gap between what you borrow at and what you earn)
Already have an advisor and don't want to fire anyone
Think 45 is too late to change the next decade
Want to see the math before you believe a word (good, that's the session)
If that's you, I want you in the room.
WHAT YOU'LL LEARN
WHAT YOU'LL
LEARN
WHAT
YOU'LL
LEARN
01
THE POWER OF THE PAYCHEQUE
Your income lands in chequing, does one job, and dies. I'll show you the structure where your paycheque pays the mortgage down years faster, frees up cash flow, and stays available for the 2 bigger moves.
02
THE THREE ROOMS
Your broker, advisor, and accountant each run their own room. The whole house goes unwatched. That's why high earners stand still.
03
THE BRACKET FLIP
How earning over $181,440 a year puts you in a tax bracket that lets you run a strategy most Canadians can't, and the roughly $4,800 that comes back on every $10,000 contributed.
04
THE TRIPLE COMPOUND, LIVE
The 3 steps, run on real client files, while you score your own household.
WHAT YOU'LL
LEARN
WHAT
YOU'LL
LEARN
01
THE POWER OF THE PAYCHEQUE
Your income lands in chequing, does one job, and dies. I'll show you the structure where your paycheque pays the mortgage down years faster, frees up cash flow, and stays available for the 2 bigger moves.
02
THE THREE ROOMS
Your broker, advisor, and accountant each run their own room. The whole house goes unwatched. That's why high earners stand still.
03
THE BRACKET FLIP
How earning over $181,440 a year puts you in a tax bracket that lets you run a strategy most Canadians can't, and the roughly $4,800 that comes back on every $10,000 contributed.
04
THE TRIPLE COMPOUND, LIVE
The 3 steps, run on real client files, while you score your own household.
WHY LIVE MATTERS
The walk-through on real client files only happens live.
The walk-through on real client files only happens live.
The replay covers the ideas. It skips the math.
Live, you also get The Two Timelines Scorecard.
Live, you also get The Two Timelines Scorecard.
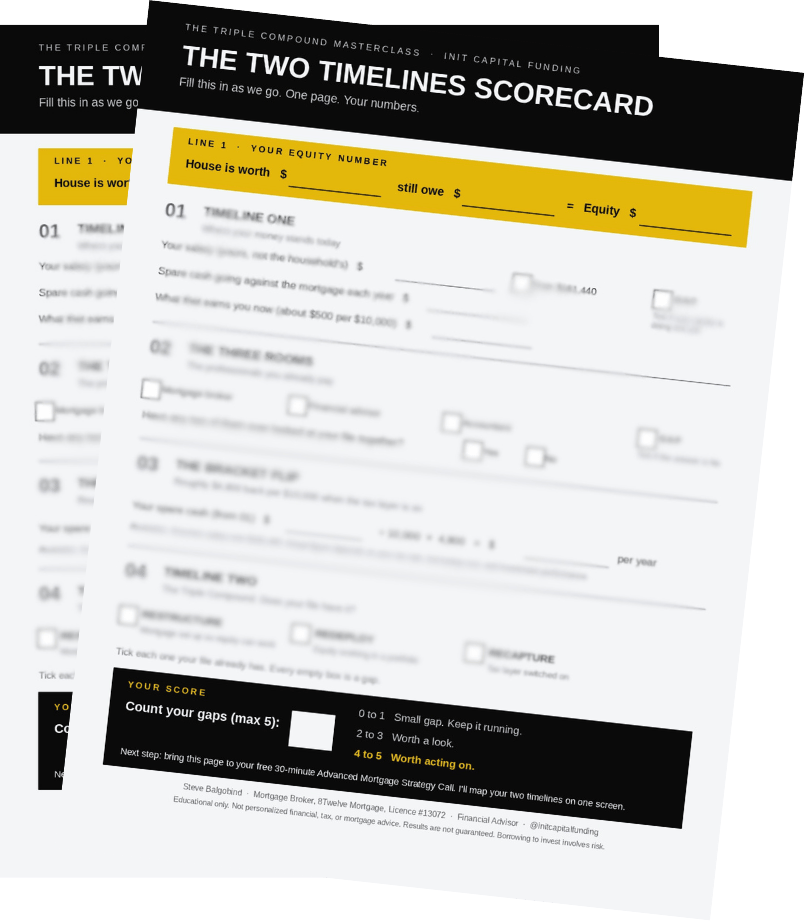
This is a one-page sheet you fill in as we go, so you leave knowing where your own money stands. It only works if you're in the room.
Block the hour. Have your mortgage statement and last year's tax return nearby.
The walk-through on real client files only happens live.
The walk-through on real client files only happens live.
The replay covers the ideas. It skips the math.
Live, you also get The Two Timelines Scorecard.
Live, you also get The Two Timelines Scorecard.
This is a one-page sheet you fill in as we go, so you leave knowing where your own money stands. It only works if you're in the room.
Block the hour. Have your mortgage statement and last year's tax return nearby.
Structure Beats Tactics
Most high earners think there are two ways ahead:
earn more, or cut back.
Most high earners think there are two ways ahead: earn more, or cut back.
THERE'S A THIRD.
Set up your mortgage, your investments, and your tax return once, so they work together instead of separately.
Set up your mortgage, your investments, and your tax return once,
so they work together instead of separately.
I run it on my own home. It's called The Triple Compound. I'll show you the same 3 steps I run with private clients, on real numbers.
Whether you ever work with me or not, the picture is yours to keep.
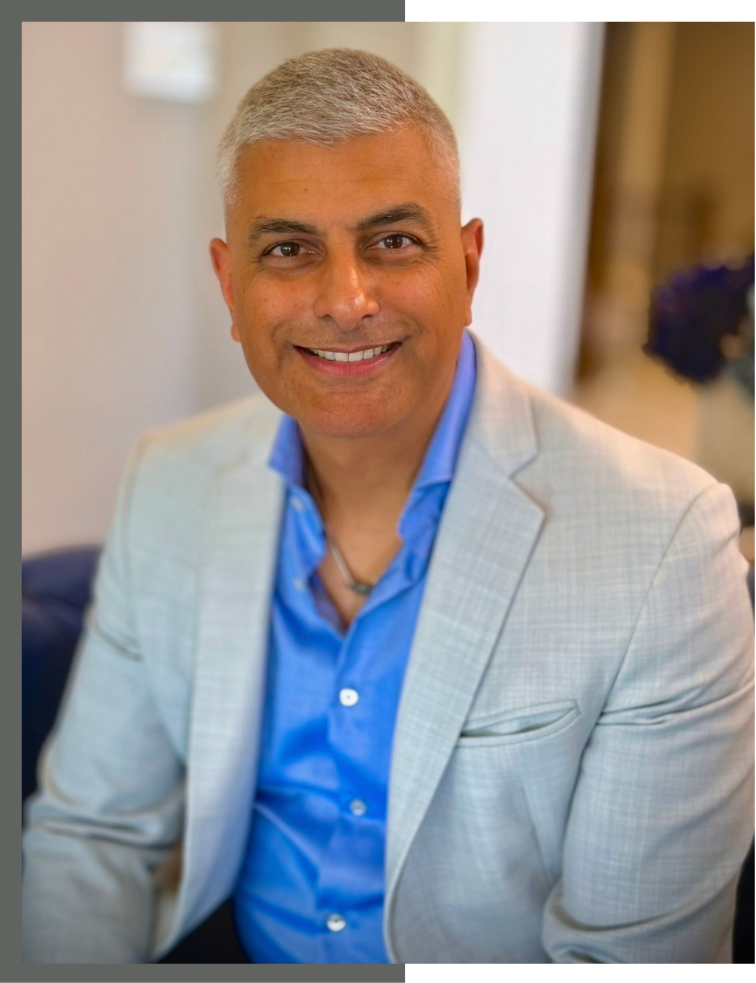
MEET YOUR HOST
I'm Steve
Balgobind
I'm Steve
Balgobind
I'm Steve Balgobind
For years I did the responsible thing. Every spare dollar against the mortgage. And every April I wondered where the raise went.
Then I ran the math on my own house. The equity was doing one job. My tax bracket was costing me every spring. I rebuilt the whole setup, and I've run it on my own home ever since.
I'm licensed as a mortgage broker and a financial advisor, and certified in the Smith Maneuver. One person looking at your mortgage, your investments, and your taxes together. That's The Household CFO.
My clients are doctors, engineers, senior managers, and tech leads across the GTA who did everything right and still stood still.
I built this masterclass because smart households keep running the average-income playbook. Sixty minutes fixes that.
TESTIMONIALS
What My Clients Are Saying
What My Clients
Are Saying
"Loved everything so far"
"Testimonial lorem ipsum dolor sit amet, consectetur adipisicing elit. Autem dolore, alias, numquam enim dolor elit."
- Insert Name
"My life changed forever"
"Testimonial lorem ipsum dolor sit amet, consectetur adipisicing elit. Autem dolore, alias, numquam enim dolor elit."
- Insert Name
"Highly recommend this"
"Testimonial lorem ipsum dolor sit amet, consectetur adipisicing elit. Autem dolore, alias, numquam enim dolor elit."
- Insert Name
Register Free
Before October 1.
Every year the default runs is a year of compounding you don't get back.
The strategy needs runway, and the math only gets run when you're in the room.
October 1 · 7:00 PM ET · Live on Zoom
Block the hour. Bring last year's tax return. See you there.
Register Free
Before October 1.
Every year the default runs is a year of compounding you don't get back. The strategy needs runway, and the math only gets run when you're in the room.
October 1 · 7:00 PM ET
Live on Zoom
Block the hour. Bring last year's tax return. See you there.
Register Free
Before October 1.
Every year the default runs is a year of compounding you don't get back. The strategy needs runway, and the math only gets run when you're in the room.
October 1 · 7:00 PM ET Live on Zoom
Block the hour. Bring last year's tax return. See you there.
WHAT'S INSIDE
01
The Two Choices
The $10,000 fork every high earner faces monthly, and what each path actually returns.
02
Your Idle Assets
Two fill-in lines that show you, in pen, what's been sitting still: your equity and your bracket.
03
The Mechanic
The worked example with round numbers, including the illustrative spread between a ~5% borrowing cost and a ~10% portfolio, and the risk disclosure that keeps it honest.
04
The Tax Layer
Why this is built for your bracket specifically: generally-deductible borrowing costs, and the ~$4,800 that comes back on a $10,000 RRSP contribution past the line.
05
What This Is Not
The honest limits: where the risk lives, why the portfolio is boring on purpose, and why faster mortgage payoff is a preference rather than the point.
06
The Two Positions
Where you are now next to the restructured position, on one page. The page worth showing your spouse.
DON'T WAIT. GET THE IDLE EQUITY PLAYBOOK NOW.
Click the button for instant access, and see your house and your income slip differently in the next 10 minutes.
Init Capital Funding | 2026 Privacy Policy · Terms of Service
Init Capital Funding | 2026
This site is not a part of the Facebook or Instagram apps or a part of Meta Inc. This site is not endorsed by Facebook or Instagram in any way. FACEBOOK and INSTAGRAM are trademarks of Meta, Inc.
Steve Balgobind, Mortgage Broker, 8Twelve Mortgage, Licence #13072. Case files are anonymized examples for illustration. Results are not guaranteed. Borrowing to invest involves risk. This session is educational and is not personalized financial, tax, or mortgage advice.