FREE LIVE MASTERCLASS · October 29, 2026 · 7:30 PM ET · ZOOM
FREE LIVE MASTERCLASS
October 29, 2026 · 7:30 PM ET · ZOOM
How GTA Homeowners Earning $200K+ Are Paying Off Their Mortgage Years Sooner AND Building a Portfolio at the Same Time
In 60 minutes, I’ll walk you through the exact structure on real client files. No earning more. No picking stocks. No selling the house.
No spam. Your confirmation and a couple of
reminders before we go live.
No spam. Your confirmation and a couple of reminders before we go live.
How GTA Homeowners Earning $200K+ Are Paying Off Their Mortgage Years Sooner AND Building a Portfolio at the Same Time
In 60 minutes, I’ll walk you through the exact structure on real client files. No earning more. No picking stocks. No selling the house.
No spam. Your confirmation and a couple of reminders before we go live.
Free. Instant. Nothing to buy, no call required to read it. Just math your bank has never laid out.
Most high-income households manage their mortgage, investments and taxes separately.
This masterclass shows you what can happen when those three pieces are designed to work together.
No earning more. No picking stocks. No selling the house.
Live only. Save your seat below.
Real Files. Real Numbers.
Two anonymized files from my desk,
plus the math on one dollar.
See how a $10,000 RRSP contribution could create a significant tax deduction for a high-income household- and what you could do with the resulting tax savings.
Real Files. Real Numbers.
Two anonymized files from my desk, plus the math on one dollar.
Two anonymized files from my desk,
plus the math on one dollar.
See how a $10,000 RRSP contribution could create a significant tax deduction for a high-income household- and what you could do with the resulting tax savings.
CASE STUDY 1
BEFORE
Age: 35
Mortgage: $670K
Investment portfolio: $0
Monthly cash flow: $2,750
Current Bank Mortgage Payoff Time frame: 27 years
PRADEEEP
CASE STUDY 2
BEFORE
Age: 55 + 56
Mortgage: $450K
Investment portfolio: $200K
Monthly cash flow: $2,750
Current Mortgage Payoff Timeframe: 19 YEARS
Mr. & Mrs. Patrick
THE TWO CHOICES
You have $10,000 of spare money.
You have two options.
Put it against the mortgage
You save about $500 in interest this year. That's the entire return. Small, certain, and gone.
PUT IT TO WORK
It earns a return in the market, becomes an asset you actually own, and, structured properly, the cost of the money you use is generally tax-deductible.
For a household earning well and sitting on real equity, the second path is the one your bank has never laid out in plain numbers. The playbook lays it out.
WHAT
YOU'LL
LEARN
The Two Assets You Own That Earn Nothing
Your equity has been sitting in drywall earning 0% since the day you bought. Your tax bracket has been treated as pure pain. The playbook shows you both as what they actually are: the two halves of an engine.
The Move Your Bank Has Never Laid Out
The worked example, in round numbers: how accessed equity gets put to work so you keep the difference between what money costs and what it earns. Every figure labelled, every figure checkable.
Why Your Bracket Is The Lever, And Yours Runs At Full Strength
Past $181,440 of individual income in Ontario, the tax system starts paying its biggest rewards on exactly the moves you're now positioned to make. Deductible borrowing costs. A $10,000 RRSP contribution returning roughly $4,800. Per person.
The Honest Limits
What this strategy is, what it costs, where the risk lives, and who it's wrong for. Written plainly, because you were going to stress-test it anyway.
Sound Familiar?
The mortgage gets paid. The RRSP gets topped up.
You're doing the responsible thing.
And every spring the tax bill lands and you wonder
where the raise went.
You've been handed tactics your whole life. A better rate.
A budgeting app. Tactics polish one room. Your wealth falls through the floor between the rooms.
The mortgage gets paid. The RRSP gets topped up. You're doing the responsible thing.
And every spring the tax bill lands and you wonder where the raise went.
You've been handed tactics your whole life. A better rate. A budgeting app. Tactics polish one room. Your wealth falls through the floor between the rooms.
THIS IS FOR YOU IF:
THIS IS FOR YOU IF:
Your household earns $200K+ (and the math sharpens further once either of you crosses $181,440 individually)
You own a GTA home with serious equity in it, $500K+ for most of my files
Your broker, advisor, and accountant have never sat in the same room
You're tired of "earn more" being the only answer
SKIP THIS IF:
The strategy can work differently for self-employed and incorporated households. This session focuses primarily on t4 employed high-income households so we can keep the examples simple.
You're still carrying high-interest consumer debt
SKIP THIS IF:
The strategy can work differently for self-employed and incorporated households. This session focuses primarily on t4 employed high-income households so we can keep the examples simple.
You're still carrying high-interest consumer debt
EVEN IF YOU
Were told borrowing to invest is "too risky" (it carries real risk, and sizing it properly for your file is exactly what the session covers)
Think borrowing costs are too high? We'll walk through the math reviewing
potential investment returns
taxes
risks
the conditions that need to be satisfied for interest deductibility
borrowing costs
Already have an advisor and don't want to fire anyone
Think 45 is too late to change the next decade
Want to see the math before you believe a word (good, that's the session)
If that's you, I want you in the room.
WHAT YOU'LL LEARN
WHAT YOU'LL
LEARN
WHAT
YOU'LL
LEARN
01
THE POWER OF THE PAYCHEQUE
Your income lands in chequing, does one job, and dies. I'll show you the structure where your paycheque pays the mortgage down years faster, frees up cash flow, and stays available for the 2 bigger moves.
02
THE THREE ROOMS
Your broker, advisor, and accountant each run their own room. The whole house goes unwatched. That's why high earners stand still.
03
THE BRACKET FLIP
How earning over $181,440 a year puts you in a tax bracket that lets you run a strategy most Canadians can't, and the roughly $4,800 that comes back on every $10,000 contributed.
04
THE TRIPLE COMPOUND, LIVE
The 3 steps, run on real client files, while you score your own household.
WHY LIVE MATTERS
The walk-through on real client files only happens live.
The walk-through on real client files only happens live.
The replay covers the ideas. It skips the math.
Live, you also get The Two Timelines Scorecard.
Live, you also get The Two Timelines Scorecard.
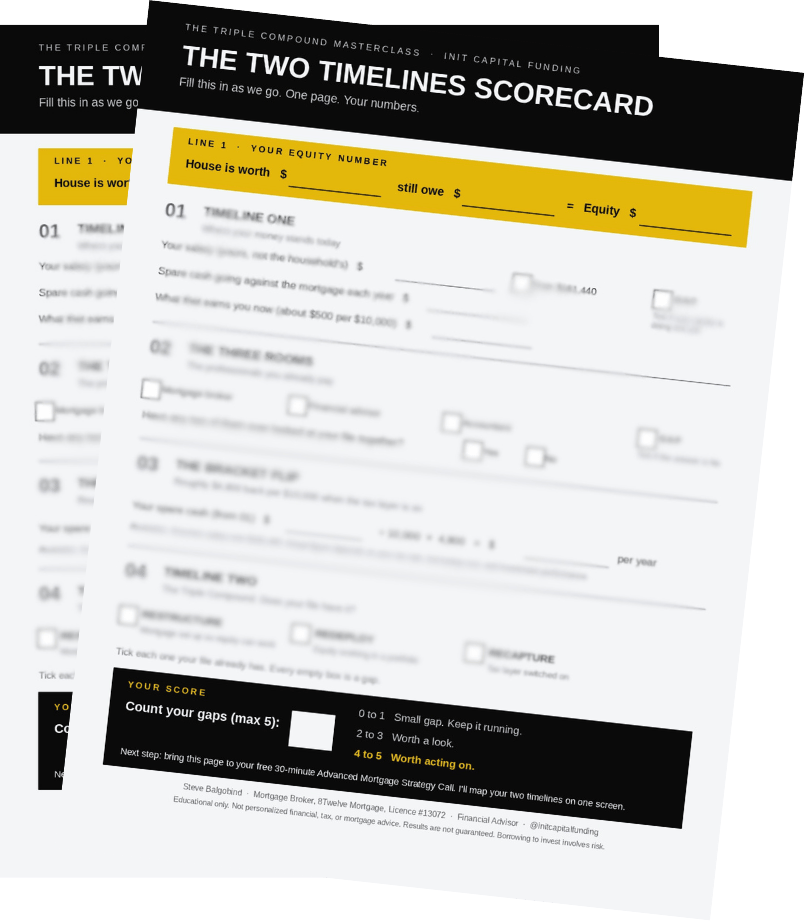
This is a one-page sheet you fill in as we go, so you leave knowing where your own money stands. It only works if you're in the room.
Block the hour. Have your mortgage statement and last year's tax return nearby.
The walk-through on real client files only happens live.
The walk-through on real client files only happens live.
The replay covers the ideas. It skips the math.
Live, you also get The Two Timelines Scorecard.
Live, you also get The Two Timelines Scorecard.
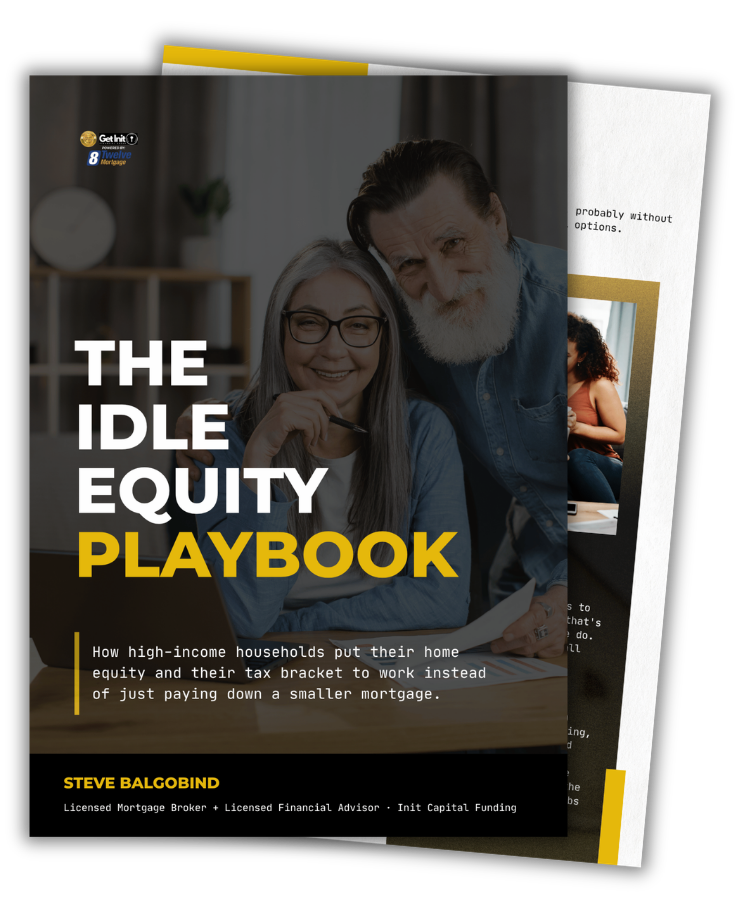
This is a one-page sheet you fill in as we go, so you leave knowing where your own money stands. It only works if you're in the room.
Block the hour. Have your mortgage statement and last year's tax return nearby.
Structure Beats Tactics
Most high earners think there are two ways ahead:
earn more, or cut back.
Most high earners think there are two ways ahead: earn more, or cut back.
THERE'S A THIRD.
Set up your mortgage, your investments, and your tax return once, so they work together instead of separately.
Set up your mortgage, your investments, and your tax return once,
so they work together instead of separately.
I run it on my own home. It's called The Triple Compound. I'll show you the same 3 steps I run with private clients, on real numbers.
Whether you ever work with me or not, the picture is yours to keep.
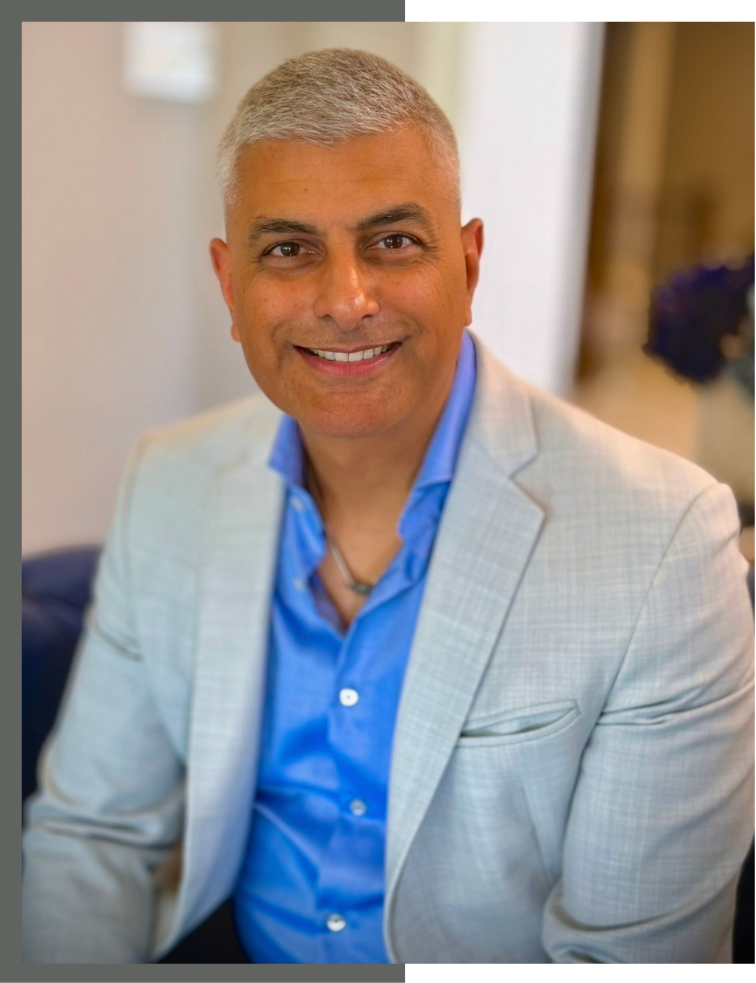
MEET YOUR HOST
I'm Steve
Balgobind
I'm Steve
Balgobind
I'm Steve Balgobind
For years I did the responsible thing. Every spare dollar against the mortgage. And every April I wondered where the raise went.
Then I ran the math on my own house. The equity was doing one job. My tax bracket was costing me every spring. I rebuilt the whole setup, and I've run it on my own home ever since.
I'm licensed as a mortgage broker and a financial advisor, and certified in the Smith Maneuver. One person looking at your mortgage, your investments, and your taxes together. That's The Household CFO.
My clients are doctors, engineers, senior managers, and tech leads across the GTA who did everything right and still stood still.
I built this masterclass because smart households keep running the average-income playbook. Sixty minutes fixes that.
TESTIMONIALS
What My Clients Are Saying
What My Clients
Are Saying
"Loved everything so far."
"I just got my mortgage two months ago and I've already dropped it down $18,000. Unbelievable! I would have never been able to do this without Steve's help."
Jennifer and Trent - Halifax, NS
"My life has changed forever."
"After my divorce I was back to square one with a $500,000 mortgage. Luckily Steve got me back on track and got me retired in 10 years to be mortgage-free. I'm back on track and in loving life!"
Mike - Cobourg, ON
"Highly recommend this."
"As a single mother of two kids, I've tried my best to pay down my mortgage but never really made a dent. When I met Steve he totally changed my life by retiring me 10 years earlier, as well as having a TFSA portfolio that I never thought possible."
Donna - Mississauga
Register Free
Before October 29, 2026.
Every year the default runs is a year of compounding you don't get back.
The strategy needs runway, and the math only gets run when you're in the room.
October 29, 2026 · 7:30 PM ET · Live on Zoom
Block the hour. Bring last year's tax return. See you there.
Register Free
Before October 29, 2026.
Every year the default runs is a year of compounding you don't get back. The strategy needs runway, and the math only gets run when you're in the room.
October 29, 2026 · 7:30 PM ET
Live on Zoom
Block the hour. Bring last year's tax return. See you there.
Register Free
Before October 29, 2026.
Every year the default runs is a year of compounding you don't get back. The strategy needs runway, and the math only gets run when you're in the room.
October 29, 2026 · 7:30 PM ET Live on Zoom
Block the hour. Bring last year's tax return. See you there.
WHAT'S INSIDE
01
The Two Choices
The $10,000 fork every high earner faces monthly, and what each path actually returns.
02
Your Idle Assets
Two fill-in lines that show you, in pen, what's been sitting still: your equity and your bracket.
03
The Mechanic
The worked example with round numbers, including the illustrative spread between a ~5% borrowing cost and a ~10% portfolio, and the risk disclosure that keeps it honest.
04
The Tax Layer
Why this is built for your bracket specifically: generally-deductible borrowing costs, and the ~$4,800 that comes back on a $10,000 RRSP contribution past the line.
05
What This Is Not
The honest limits: where the risk lives, why the portfolio is boring on purpose, and why faster mortgage payoff is a preference rather than the point.
06
The Two Positions
Where you are now next to the restructured position, on one page. The page worth showing your spouse.
DON'T WAIT. GET THE IDLE EQUITY PLAYBOOK NOW.
Click the button for instant access, and see your house and your income slip differently in the next 10 minutes.
Init Capital Funding | 2026 Privacy Policy · Terms of Service
Init Capital Funding | 2026
This site is not a part of the Facebook or Instagram apps or a part of Meta Inc. This site is not endorsed by Facebook or Instagram in any way. FACEBOOK and INSTAGRAM are trademarks of Meta, Inc.
Steve Balgobind, Mortgage Broker, 8Twelve Mortgage, Licence #13072. Case files are anonymized examples for illustration. Results are not guaranteed. Borrowing to invest involves risk. This session is educational and is not personalized financial, tax, or mortgage advice.